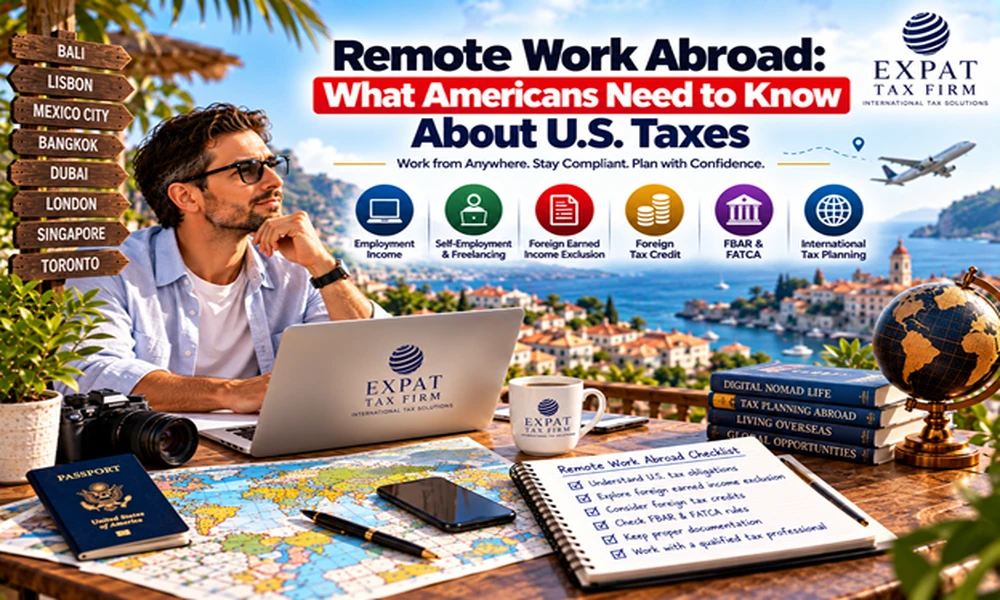

Remote work has made it easier for Americans to live and work in countries far from the United States. A laptop and reliable internet connection can allow an employee, freelancer, consultant or business owner to continue earning income while living overseas. However, working remotely from another country can create tax considerations that are easy to overlook.
For U.S. citizens and resident aliens, moving abroad generally does not eliminate U.S. tax responsibilities. The Internal Revenue Service explains that U.S. citizens and resident aliens living overseas are generally subject to U.S. tax on worldwide income and may still have U.S. filing requirements while abroad.
The rules become more important when remote work involves foreign employers, self-employment, foreign bank accounts, international clients or a long-term move to another country.
How Remote Employment Income Is Treated
One of the first questions for a remote worker is where the work is physically performed. The IRS explains that the source of earned income generally depends on where the services are performed, rather than simply where an employer is located or where payment is deposited. For example, compensation for services performed in a foreign country can generally be considered foreign earned income even when the employer is based in the United States.
This distinction can matter for Americans working remotely from countries such as Thailand, Spain, Portugal, Mexico or Australia. The taxpayer may need to consider both U.S. reporting requirements and the tax rules of the country where the work is physically performed.
Local residency rules can also become relevant. Spending significant time in another country may create tax obligations under that country’s domestic law, depending on factors such as the individual’s days of presence, residence status, income and local circumstances.
Self-Employment and Freelance Work
Remote work is not limited to traditional employees. Many Americans abroad operate as freelancers, consultants, contractors or online business owners.
The IRS states that U.S. citizens and residents who are self-employed generally remain subject to U.S. self-employment tax rules while living abroad. Net earnings from self-employment of at least $400 can trigger self-employment tax requirements. Importantly, the foreign earned income exclusion does not automatically eliminate self-employment tax.
For this reason, a freelancer working from another country should not assume that qualifying for an income exclusion means all U.S. tax obligations disappear. Business income, deductible expenses, self-employment tax and other reporting requirements may need to be considered separately.
Foreign Earned Income Exclusion
The foreign earned income exclusion is one of the provisions frequently considered by Americans working overseas. Under IRS rules, eligible taxpayers may be able to exclude a portion of qualifying foreign earned income if they meet specific requirements.
The IRS states that eligibility generally requires a foreign tax home and foreign earned income, along with satisfaction of either the bona fide residence test or the physical presence test. Form 2555 is generally used to claim the foreign earned income exclusion.
The exclusion is not automatic simply because someone works remotely outside the United States. Eligibility depends on the taxpayer’s particular circumstances and whether the applicable requirements are satisfied.
Foreign Tax Credit
Americans working abroad may also encounter foreign income taxes imposed by the country where they live or work. The foreign tax credit can potentially provide relief when qualifying foreign taxes are paid or accrued on income that is also subject to U.S. tax.
The IRS explains that taxpayers may be able to claim either a foreign tax credit or an itemized deduction for qualifying foreign income taxes, subject to applicable rules and limitations.
The interaction between the foreign tax credit and the foreign earned income exclusion is particularly important. Foreign taxes associated with income excluded under the foreign earned income exclusion generally cannot also be claimed as a foreign tax credit on that same excluded income.
Documentation Matters
Good record keeping is an important part of remote work abroad. Americans working internationally may need documentation showing income received, dates and locations of work, foreign taxes paid, business expenses, foreign account information and other relevant financial details.
Foreign currency also needs attention. The IRS states that amounts reported on a U.S. tax return generally must be expressed in U.S. dollars, meaning taxpayers receiving income or paying expenses in foreign currency need an appropriate method of converting those amounts.
Foreign financial accounts can create separate reporting requirements. For example, an FBAR generally applies when the aggregate value of qualifying foreign financial accounts exceeds $10,000 at any time during the calendar year. Other foreign asset reporting, including Form 8938 in applicable circumstances, may also need to be considered.
Where Mitchell Propster Fits In
The complexity of international tax matters has created demand for professionals who focus specifically on Americans living and working abroad. Mitchell Propster is identified by Expat Tax Firm as its founder, while the firm’s team page identifies him as CTC, Team Leader.
Expat Tax Firm publicly lists services including expat tax returns, expat business taxes, international tax planning, FBAR and foreign reporting, FATCA compliance, foreign corporations, PFIC income and small business compliance. Its Strategic Tax Review service also addresses areas such as residency planning, foreign income, international business structures and cross-border compliance.
Readers interested in Mitchell Propster’s professional background can visit Mitchell Propster on LinkedIn, while information about the firm’s services is available at Expat Tax Firm.
Frequently Asked Questions
Do Americans working remotely abroad still have to file U.S. taxes?
Generally, U.S. citizens and resident aliens remain subject to U.S. tax rules on worldwide income while living abroad. Filing requirements depend on individual circumstances.
Does working remotely automatically qualify someone for the foreign earned income exclusion?
No. Specific requirements involving a foreign tax home and either the bona fide residence or physical presence test generally apply.
Can freelancers abroad be subject to U.S. self-employment tax?
Yes. U.S. citizens and residents who are self-employed abroad generally remain subject to U.S. self-employment tax rules, subject to the applicable requirements and exceptions.
Should remote workers keep records of their time abroad?
Maintaining accurate records can be important for determining eligibility for certain tax provisions and documenting income, expenses and foreign tax payments.
Remote work can provide significant flexibility, but international mobility can also introduce additional tax and reporting responsibilities. Understanding the interaction between U.S. rules, foreign-country requirements, income exclusions, tax credits and financial reporting can help Americans working abroad approach their obligations more systematically.
This article is for general informational purposes only and does not constitute tax, legal or financial advice. Individual U.S. and foreign tax obligations vary according to personal circumstances, residency, income and applicable laws.
Remote Work Abroad: What Americans Need to Know About U.S. Taxes